Aldi Business Model: How a 2.3% Margin Grocer Makes Money
The Aldi business model explained: a short own-brand range, small low-cost stores and huge volumes, all to keep about 2.3p of profit from every £1 of sales.
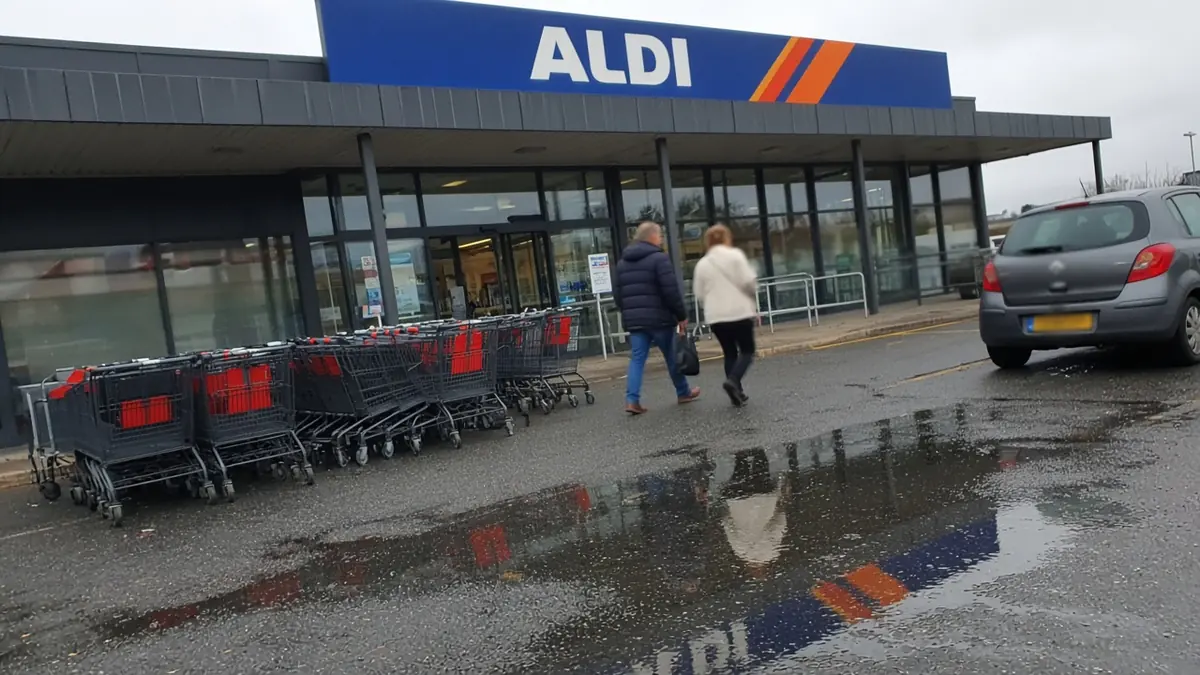
Aldi’s business model is simple: sell a short list of mostly own-brand groceries from small, cheap-to-run stores, price them low enough to pull in huge volumes, and live on a very thin margin. In the UK, the one market where Aldi publishes detailed annual results, it kept about 2.3p of operating profit from every £1 of sales in 2025.
That tiny number explains almost everything else about the chain, from the quarter you drop into the cart to the barcodes printed on every side of the box.
Key takeaways
- Aldi earns its money from one thing: selling groceries and household goods. There’s no membership fee, and Aldi says more than 90% of what it sells is its own label.
- Aldi UK made £432.9m of operating profit on £19bn of 2025 sales. That 2.3% margin is down from about 3.1% in 2023.
- Aldi is private. Aldi US belongs to Aldi Süd, which is held by Albrecht family foundations, so there is no Aldi stock to buy.
- Aldi US is aiming for 3,200 stores by the end of 2028, while in the UK, Lidl is currently growing faster.
How does Aldi make money?
Aldi makes money the old-fashioned way. It buys products cheaply, sells them for slightly more, and repeats that millions of times a day.
There’s no paid membership like Costco’s, no loyalty scheme to fund, and no big portfolio of national brands paying for shelf space. Almost all revenue is the checkout total.
Within that, three things pull shoppers through the door:
- Everyday groceries. The bulk of sales: milk, bread, produce, meat, pantry staples, all at prices designed to undercut the big chains.
- Weekly non-food deals. Called Aldi Finds in the US and Specialbuys in the UK. Garden furniture one week, air fryers the next. They create urgency and add unplanned items to the basket.
- Online orders. Aldi US offers curbside pickup and delivery through shop.aldi.us, though the stores remain the engine.
One thing Aldi doesn’t do is publish a revenue split. No market breaks out food versus non-food, and Aldi US doesn’t report its sales at all. Any exact Aldi US revenue figure you see online is an estimate, not a disclosure.
Five cost decisions that make the model work
Low prices are the output. These five choices are the input.
1. Far fewer products
A conventional supermarket stocks tens of thousands of items. Aldi’s range is commonly cited at under 2,000. Fewer items means much bigger orders per item, better buying prices, faster-selling shelves and stores that are easier to run.
2. Own label first
Aldi says more than 90% of its products are its own label. Aldi writes the spec and suppliers compete on cost, so shoppers aren’t paying for a national brand’s advertising. In 2025, Aldi US started putting the Aldi name itself on that packaging to make the store brands easier to spot.
3. Shelf-ready packaging
Many products arrive in cartons that go straight onto the shelf. Staff tear off a panel instead of stacking items one by one. Large barcodes on several sides of the pack speed up scanning at checkout.
4. Customers do some of the work
The cart deposit (a quarter in the US) means nobody is paid to round up carts in the parking lot. You bring or buy your own bags and pack at a separate shelf, so the cashier can start on the next customer straight away.
5. Small stores, lean crews
Aldi stores are small by US standards and lightly staffed. Less floor space means less rent, heating and cleaning per store, and fewer products means fewer people needed to manage them.
None of these choices is clever on its own. Stacked together, they let Aldi charge less and still make a profit, which is the whole point. Aldi’s stated core values of simplicity, consistency and responsibility read like a description of this machine; we unpacked them in our guide to Aldi’s core values.
The numbers: what Aldi UK’s accounts show
Aldi UK is the best window into the economics because it publishes annual sales and profit. The figures below cover Aldi’s UK and Ireland business for years ending December 31.
| Year | Sales | Operating profit | Operating margin |
|---|---|---|---|
| 2023 | £17.9bn | £552.9m | 3.1% (calculated) |
| 2024 | £18.1bn | £435.5m | 2.4% |
| 2025 | £19.0bn | £432.9m | 2.3% |
Source: Aldi UK annual results (September 2025 and September 2026), as reported by Reuters and the UK trade press.
Here’s the calculation that matters. If Aldi had kept its 2023 margin on its 2025 sales, operating profit would have been about £587m. It actually reported £432.9m.
That gap of roughly £150m a year is what Aldi has chosen to spend on lower prices, higher pay and new infrastructure, the three reasons it gave for the fall. It’s the price war, expressed as one number.
Where each £1 of Aldi UK sales went in 2025
Operating profit was 2.3% of sales. On a £50 weekly shop, that’s about £1.14 for Aldi.
Who owns Aldi? Is Aldi publicly traded?
No, Aldi isn’t publicly traded. There’s no ticker and no Aldi shares to buy.
Brothers Karl and Theo Albrecht built the chain in Germany and split it in 1961 into two separate companies: Aldi Süd (Karl) and Aldi Nord (Theo). Aldi Süd runs the Aldi stores in the US, UK, Ireland and Australia.
Aldi Süd is owned by Albrecht family foundations, with the Siepmann-Stiftung reported to hold at least 75%. Trader Joe’s sits on the other side of the family: it’s owned by families that also own part of Aldi Nord, and Trader Joe’s says it has no business or ownership relationship with Aldi Süd.
Compare that with Walmart, which is listed on the stock market but still controlled by the Walton family; we break down who owns Walmart separately.
Is Aldi a German company?
Yes. Aldi Süd is based in Mülheim an der Ruhr. Aldi US has its own headquarters in Batavia, Illinois, and opened its first American store in Iowa in 1976.
My take: private ownership is part of the business model, not a footnote. A listed grocer whose margin fell from 3.1% to 2.3% in two years would face hard questions on every earnings call. Aldi’s owners can simply accept it if it protects prices and market share.
Where Aldi is spending the money
The thin margin still produces a lot of cash at Aldi’s scale, and almost all of it goes into more stores.
In the US, Aldi said in January 2026 that it would open more than 180 stores this year, reaching nearly 2,800 by year end, on the way to 3,200 stores by the end of 2028. That’s part of a five-year, $9bn plan. It’s also converting former Winn-Dixie and Harveys supermarkets, bought with Southeastern Grocers in 2024, into Aldi stores, and says 17 million new customers shopped with it in 2025.
In the UK, Aldi announced £1.6bn of investment over two years in September 2025, when it had 1,060 stores and a stated ambition of 1,500.
Where the Aldi business model is weak
The model is strong, but it isn’t bulletproof. Four pressure points stand out.
- Little room for error. UK sales rose 5% in 2025, yet operating profit slipped slightly. At a 2.3% margin, a modest rise in wages or energy costs can wipe out a year’s growth.
- Lidl is copying the playbook and winning share. Industry data reported by Reuters showed Aldi UK’s sales up 0.7% in the 12 weeks to September 6, 2026, against 8% at Lidl GB. Aldi’s UK share was 10.6%, down 0.2 points on the year.
- A short range caps the basket. If you want a specific brand of cereal or diapers, you still need a second shop. That limits how much of a household’s grocery spend Aldi can win.
- Delivery cuts against the design. The store model exists to strip out labour. Picking and delivering orders adds labour back, which is why stores, not apps, still carry the business.
The quarter in the cart slot isn’t a gimmick. It’s the whole Aldi business model in miniature: a small cost removed, handed back as a lower price, and repeated across thousands of stores.
Discussion